Can You Have Two VA Loans at the Same Time? What Most Veterans Don't Know About Their VA Loan Benefit
You may be able to keep your current home, turn it into a rental, and purchase another home using your VA loan benefit—with little or no down payment.
By Justin Taylor | The Fly Mortgage Guy
One of the most common misconceptions I hear from veterans is that you can only have one VA loan at a time.
Maybe you purchased a home several years ago using your VA loan benefit. Since then, your family has grown, you've received PCS orders, or a new career opportunity is taking you somewhere else.
You'd like to keep your current home, perhaps because you have a great interest rate or want to turn it into a rental property.
But there's a problem—or at least you think there is.
You already have a VA loan.
Here's what many veterans don't realize: You can absolutely have two VA loans at the same time.
In fact, depending on your remaining VA entitlement, you may even be able to purchase your next home without a down payment.
The key is understanding how your VA loan entitlement works.
First, Let's Clear Up a Major Misconception
The VA home loan is not a one-time benefit.
Eligible veterans can use their VA home loan benefit multiple times throughout their lives. There's no lifetime limit on the number of times you can use it.
Even more importantly, you don't necessarily need to pay off an existing VA loan before obtaining another.
In September 2026, the Department of Veterans Affairs specifically addressed this misconception in an article explaining that veterans can use their VA home loan benefit more than once—even while maintaining another VA-backed mortgage.
Read the VA's official explanation here.
That can create significant opportunities for military families and veterans who need to relocate but don't necessarily want to sell their current home.
However, just because you can have two VA loans doesn't automatically mean you qualify for another zero-down purchase.
That's where entitlement comes into play.
What Is VA Loan Entitlement?
VA loan entitlement is the amount of guaranty the Department of Veterans Affairs provides to a lender on your behalf.
In simple terms, the VA agrees to cover a portion of the lender's loss if a qualifying borrower defaults on the mortgage.
That guaranty is one of the reasons lenders can offer VA loans with benefits such as no required down payment in many circumstances and no monthly private mortgage insurance.
For most VA loans, lenders look for a combination of VA guaranty and any down payment that provides coverage equal to at least 25% of the loan amount.
There are two important concepts to understand.
Full entitlement: If you have full entitlement, the VA doesn't impose a county loan limit on the amount you can borrow without a down payment. Your actual borrowing power still depends on lender approval, income, credit, and the property's value.
Remaining entitlement: If you've already used some of your VA entitlement and it hasn't been restored, the amount available for your next purchase may be limited.
You may also hear the term second-tier entitlement or bonus entitlement. This refers to additional entitlement available for larger VA loans.
It's not a separate benefit that you have to earn. It's part of the VA guaranty structure.
And it's often what makes having two VA loans possible.
Learn more about VA entitlement and loan limits directly from the VA.
How Does Having Two VA Loans Actually Work?
Let's look at a real-world-style example.
Imagine you're an Air Force veteran who purchased your first home several years ago.
You bought the home for $300,000 using a VA loan with zero down.
Now you've received an attractive job offer in another state, and your family needs to move.
Your existing home has a low mortgage rate, and you'd prefer to rent it out rather than sell it.
You find another house for $450,000.
Can you use your VA loan benefit again?
Potentially, yes.
The answer depends largely on how much entitlement is still available and whether you qualify financially to carry the new mortgage.
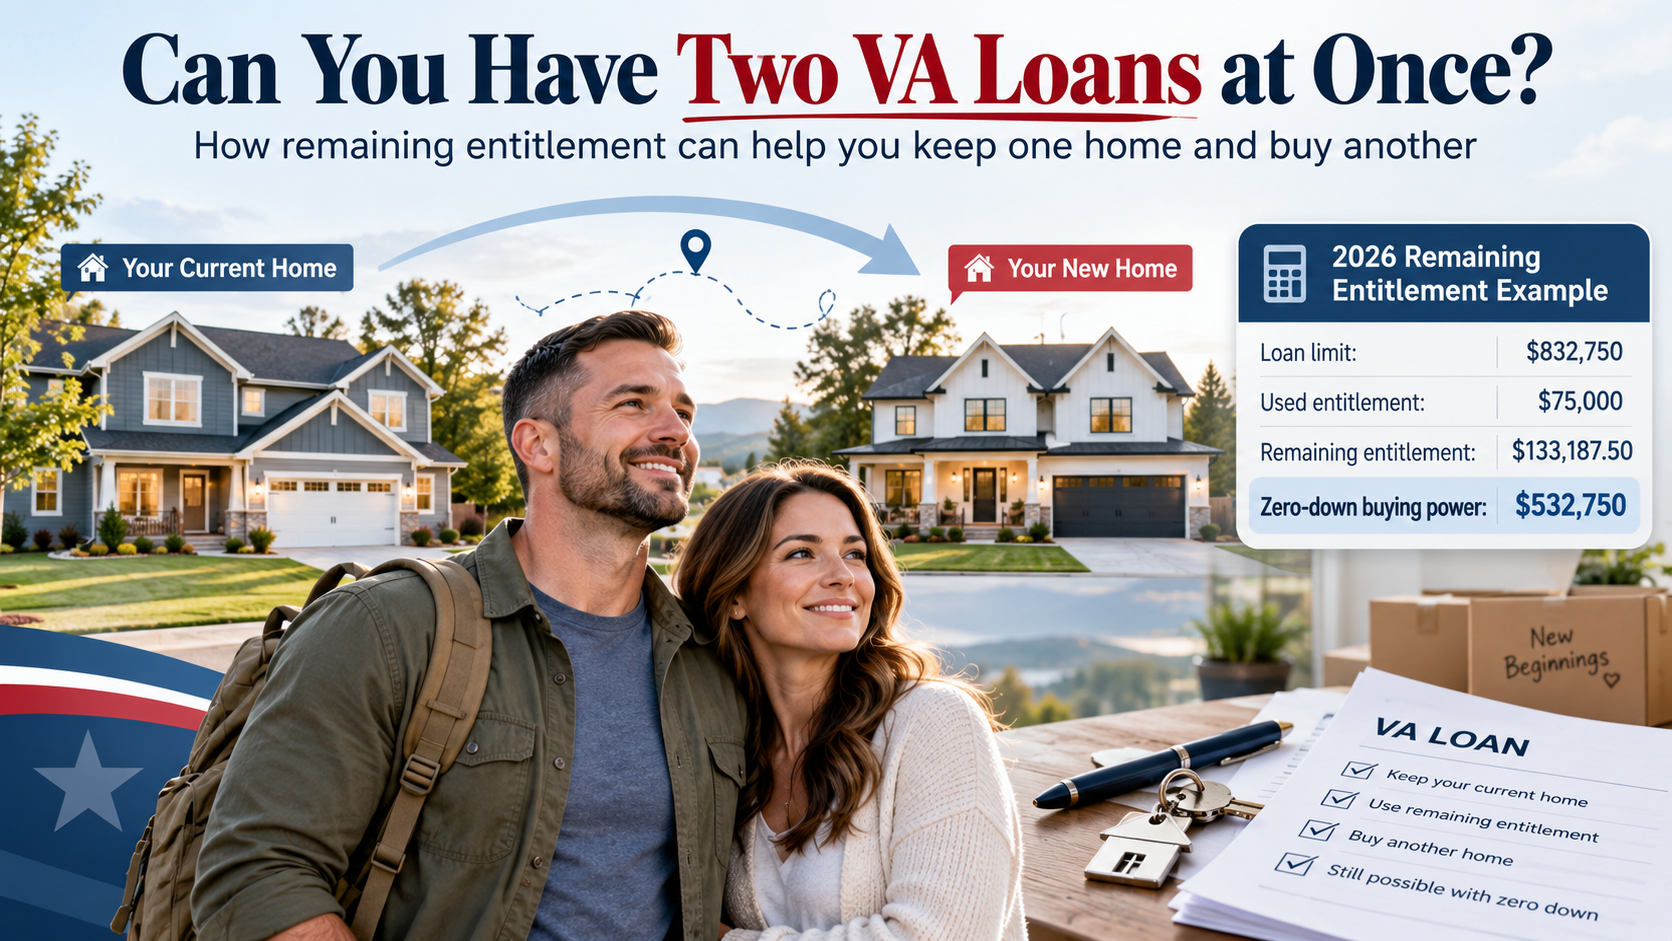
Understanding the Numbers: 2026 VA Entitlement Example
For this example, let's assume:
Your original VA loan was $300,000.
The entitlement charged to your original loan was $75,000.
The new home costs $450,000.
The new property is located in a county with the standard 2026 conforming loan limit of $832,750.
The VA generally calculates your available guaranty using 25% of the applicable county loan limit, then subtracts entitlement already used.
Here's how the math works:
Calculation | Amount |
|---|---|
2026 baseline conforming loan limit | $832,750 |
Maximum guaranty (25%) | $208,187.50 |
Entitlement already used | −$75,000 |
Remaining entitlement | $133,187.50 |
Potential zero-down loan capacity | $532,750 |
The final step is multiplying your remaining entitlement by four.
$133,187.50 × 4 = $532,750
In this scenario, the veteran has enough remaining entitlement to support a $450,000 purchase without a down payment, assuming the lender approves the transaction and the property meets VA requirements.
And just like that, the veteran could have two active VA loans.
One on the original property, which may now be rented out.
And another on the new primary residence.
The veteran didn't need to sell the original house, pay off the low-interest mortgage, or automatically come up with a large down payment.
That's a powerful option that many veterans overlook.
Important note about 2026 loan limits: The standard conforming loan limit for a one-unit property in most U.S. counties is $832,750 for 2026. Certain high-cost areas and special geographic locations have higher limits. These limits matter when calculating remaining VA entitlement; they do not create a VA-imposed borrowing cap for veterans with full entitlement.
You can verify the official 2026 conforming loan limits through the Federal Housing Finance Agency.
What If You Don't Have Enough Remaining Entitlement?
This is another area where veterans often receive incomplete information.
Let's continue using our original example.
The veteran has $133,187.50 in remaining entitlement, enough to support a zero-down loan of approximately $532,750.
But what if the new home costs $600,000 instead of $450,000?
Does that mean the veteran is ineligible for another VA loan?
Not necessarily.
You may still qualify by making a down payment sufficient to cover the guaranty shortfall.
Using our example:
Calculation | Amount |
|---|---|
New home purchase price | $600,000 |
Required 25% coverage | $150,000 |
Remaining VA entitlement | $133,187.50 |
Coverage shortfall | $16,812.50 |
Illustrative down payment | $16,812.50 |
Rather than needing a conventional 20% down payment of $120,000, this veteran may be able to obtain another VA loan with a down payment of approximately $16,813.
That's about 2.8% of the purchase price.
The exact calculation depends on the available entitlement, loan amount, appraisal, and lender requirements. Any applicable VA funding fee and other closing costs must also be considered separately.
But the lesson is important.
Having insufficient entitlement for a zero-down purchase doesn't necessarily mean you can't use your VA benefit again.
It may simply mean a partial down payment is necessary.
Can You Keep Your Current Home and Rent It Out?
Yes, this can be possible.
VA loans are intended to finance primary residences, but that doesn't mean you must live in the same property forever.
Your original intention to occupy the property when you purchased it matters.
If you legitimately occupied the property as your primary residence and later need to relocate, converting it into a rental doesn't automatically violate the original loan's occupancy requirement.
For example, military members frequently receive PCS orders that require them to move to another duty station.
Rather than selling their home, they may decide to retain it as an investment property.
The new VA loan must still be used for an eligible primary residence, and the borrower must satisfy the applicable occupancy requirements.
You cannot simply purchase a vacation home or an investment property using a VA purchase loan while pretending you intend to occupy it.
But a legitimate relocation from one primary residence to another is a different situation entirely.
This is particularly important for military families who move frequently and want to begin building a real estate portfolio over time.
Will the Rental Income From My First Home Help Me Qualify?
Potentially—and this can make a substantial difference.
When purchasing another home, your lender must evaluate your ability to repay the mortgage.
If you retain your first property, the existing mortgage payment generally remains part of your financial obligations.
However, qualifying rental income from that property may be considered under the applicable VA underwriting guidelines.
Depending on your rental history, property circumstances, and lender requirements, the lender may request:
An executed lease agreement.
Evidence of rent payments or deposits.
Tax returns documenting rental-income history.
Documentation of the property's housing expenses.
Required cash reserves.
One important distinction: Not all anticipated rental income can automatically be used to qualify for your next mortgage.
VA underwriting requirements distinguish between established rental properties and properties being converted from a primary residence into rentals. The documentation, income calculation, and reserve requirements may differ.
For example, a property that rents for $2,500 per month doesn't necessarily provide $2,500 in usable qualifying income.
Your lender must determine what income, if any, can be counted and how it affects your overall financial qualifications.
This is a particularly important discussion to have before listing your current home for rent or signing a purchase contract on the next one.
Does Your VA Entitlement Come Back When You Pay Down Your Mortgage?
No—and this is an important distinction.
Your available entitlement isn't based on the current principal balance of your mortgage.
Let's say your original VA loan was $300,000, and you've paid the balance down to $200,000.
That doesn't automatically mean you've recovered $100,000 worth of borrowing capacity.
The amount of entitlement originally charged to the loan generally remains committed until it is eligible for restoration.
Simply making mortgage payments and building equity doesn't restore your VA entitlement.
Similarly, refinancing your existing VA loan into a conventional mortgage doesn't automatically restore entitlement if you continue owning the property.
There is, however, a potentially valuable exception.
The One-Time VA Entitlement Restoration Rule
The VA allows certain veterans to restore previously used entitlement even when they keep the property.
Generally, if you've paid off the VA loan in full but still own the home, you may qualify for a one-time restoration of entitlement.
This can be particularly useful for veterans considering refinancing an existing VA mortgage into a conventional loan.
But here's the catch.
This type of restoration can generally only be used once.
You should carefully consider whether using that one-time opportunity now makes sense for your longer-term real estate plans.
For example, if you refinance your current VA loan into a conventional mortgage, pay off the original VA loan in full, and obtain your one-time restoration, you could potentially use your restored entitlement toward another primary residence.
That doesn't necessarily make refinancing the right financial decision.
If you're giving up a 2.75% VA mortgage to obtain a significantly higher conventional rate, the additional borrowing flexibility could come at a substantial cost.
The right answer depends on the entire strategy.
Other entitlement restoration options may be available when you sell a property and pay off the VA loan, or when a qualified veteran assumes the loan and substitutes their entitlement.
Review the VA's official entitlement restoration and eligibility requirements.
What About the VA Funding Fee on Your Second Loan?
Using your VA loan benefit again can also affect the VA funding fee.
For most nonexempt borrowers purchasing a home with less than 5% down, the funding fee increases from 2.15% on first use to 3.30% on subsequent use.
However, making a down payment of at least 5% reduces the fee to 1.50%, even for subsequent users.
A down payment of at least 10% reduces it further to 1.25%.
And qualifying veterans receiving service-connected disability compensation may be exempt from the funding fee entirely.
This creates an interesting financial planning opportunity.
Even if your remaining entitlement allows you to purchase another home with zero down, you may want to compare the cost of putting 5% down to reduce the funding fee.
For some veterans, that strategy can save thousands of dollars. For others, preserving cash may be more valuable.
The best option isn't always the one with the smallest down payment.
It's the one that makes the most sense for your overall financial situation.
For a more detailed breakdown of funding fee rates, exemptions, and strategies, read my guide:
The VA Funding Fee Explained: What Every Veteran Should Know Before Buying a Home
Four Things Veterans Should Consider Before Taking Out a Second VA Loan
1. Your Existing Mortgage Rate
If you purchased or refinanced when mortgage rates were unusually low, that mortgage could be a valuable financial asset.
Selling your home or refinancing unnecessarily could mean giving up financing terms that are difficult to replace.
Before making that decision, evaluate whether retaining the home makes financial sense.
2. Your Available Entitlement
Don't assume you have to sell your house to qualify for another VA loan.
Review your Certificate of Eligibility (COE) and have a mortgage professional calculate your remaining entitlement using the loan limit for the county where you plan to purchase.
Your COE identifies entitlement previously charged to VA loans, which is a key number in determining your available benefit.
You may be surprised by how much purchasing power you still have available.
3. Your Ability to Carry Two Properties
Keeping your first home can be a good long-term investment strategy, but it also introduces financial responsibilities.
Even with rental income, you need to consider maintenance, vacancies, repairs, property taxes, insurance, and the possibility of covering both mortgage payments.
Owning a rental property can be a great way to build wealth, but it's important to make sure you have the financial flexibility to handle the unexpected.
4. Your Long-Term Goals
Homeownership decisions should support your life, not unnecessarily restrict it.
Keeping a property because you have a low interest rate isn't automatically the right financial decision.
Likewise, selling a property simply because you believe you can't have two VA loans could mean giving up an opportunity you didn't realize existed.
The best decision considers your finances, career, family, and long-term goals.
Frequently Asked Questions About Having Multiple VA Loans
Can I have two VA loans at the same time?
Yes. Eligible veterans can have two active VA-backed home loans if they have sufficient remaining entitlement or meet any applicable down payment requirements, satisfy occupancy rules, and qualify with their lender.
Can I have three VA loans at the same time?
Potentially, yes. There is no specific lifetime limit on how many times you can use your VA home loan benefit. Having three simultaneous VA loans would depend on having sufficient remaining entitlement, satisfying occupancy requirements for each new loan, and qualifying financially.
Can I use a VA loan to buy a second home?
You can use your VA benefit again to purchase another eligible primary residence. You generally cannot use a VA purchase loan solely to acquire a vacation home or investment property.
Do I need to sell my current house to use my VA loan again?
No. Depending on your remaining entitlement and financial qualifications, you may be able to retain your existing home.
Can I rent out my first VA-financed house?
Yes, potentially. If you originally purchased and occupied the home in good faith as your primary residence, a later legitimate change in circumstances may allow you to convert the home into a rental.
How much VA entitlement do I have left?
Your remaining entitlement generally depends on the entitlement already charged to your existing VA loans and the applicable county loan limit for your next purchase.
Your Certificate of Eligibility is the starting point for this calculation.
Does my remaining entitlement mean I can't borrow more than that amount?
No. VA entitlement is a guaranty amount, not your mortgage borrowing limit. Most lenders use the available guaranty to determine how much you can borrow without a down payment.
You may still be able to borrow more by making an appropriate down payment and meeting the lender's financial requirements.
How many times can I use my VA loan benefit?
There is no lifetime limit on the number of times an eligible veteran can use the VA home loan benefit, although entitlement availability and other requirements still apply.
Does refinancing my VA loan into a conventional mortgage restore my entitlement?
Not automatically. If the existing VA loan is fully repaid while you retain the property, you may qualify for the VA's one-time restoration provision.
The Bottom Line
The VA home loan benefit is far more flexible than many veterans realize.
Having an existing VA mortgage doesn't automatically prevent you from using the benefit again.
You may be able to keep your current home, retain a favorable mortgage rate, convert the property into a rental, and purchase another primary residence with little or no money down.
The key is understanding your remaining entitlement, occupancy requirements, and financial qualifications before making a decision.
As a veteran and former military pilot, I understand how frequently military careers and family circumstances require us to relocate.
And as a mortgage broker specializing in VA financing, I've seen how understanding these guidelines can open doors that veterans didn't even realize existed.
Before you sell your home or assume you've exhausted your VA benefit, find out what options are actually available to you.
You've earned this benefit. Make sure you're making the most of it.
Justin Taylor | The Fly Mortgage Guy
Former C-17 Pilot | USAF Veteran | Independent Mortgage Broker
This article is intended for educational purposes. All loans are subject to borrower qualification, lender requirements, and applicable VA guidelines. Examples are illustrative and do not constitute a financing offer.